Bottom-up requests
Sites identify real needs, but no site is responsible for weighing its request against opportunities elsewhere in the business.
Strategic capital allocation
A systems approach compares strategic alternatives on company-wide cash flow, so capital follows what the combination delivers rather than what each project returns on its own.
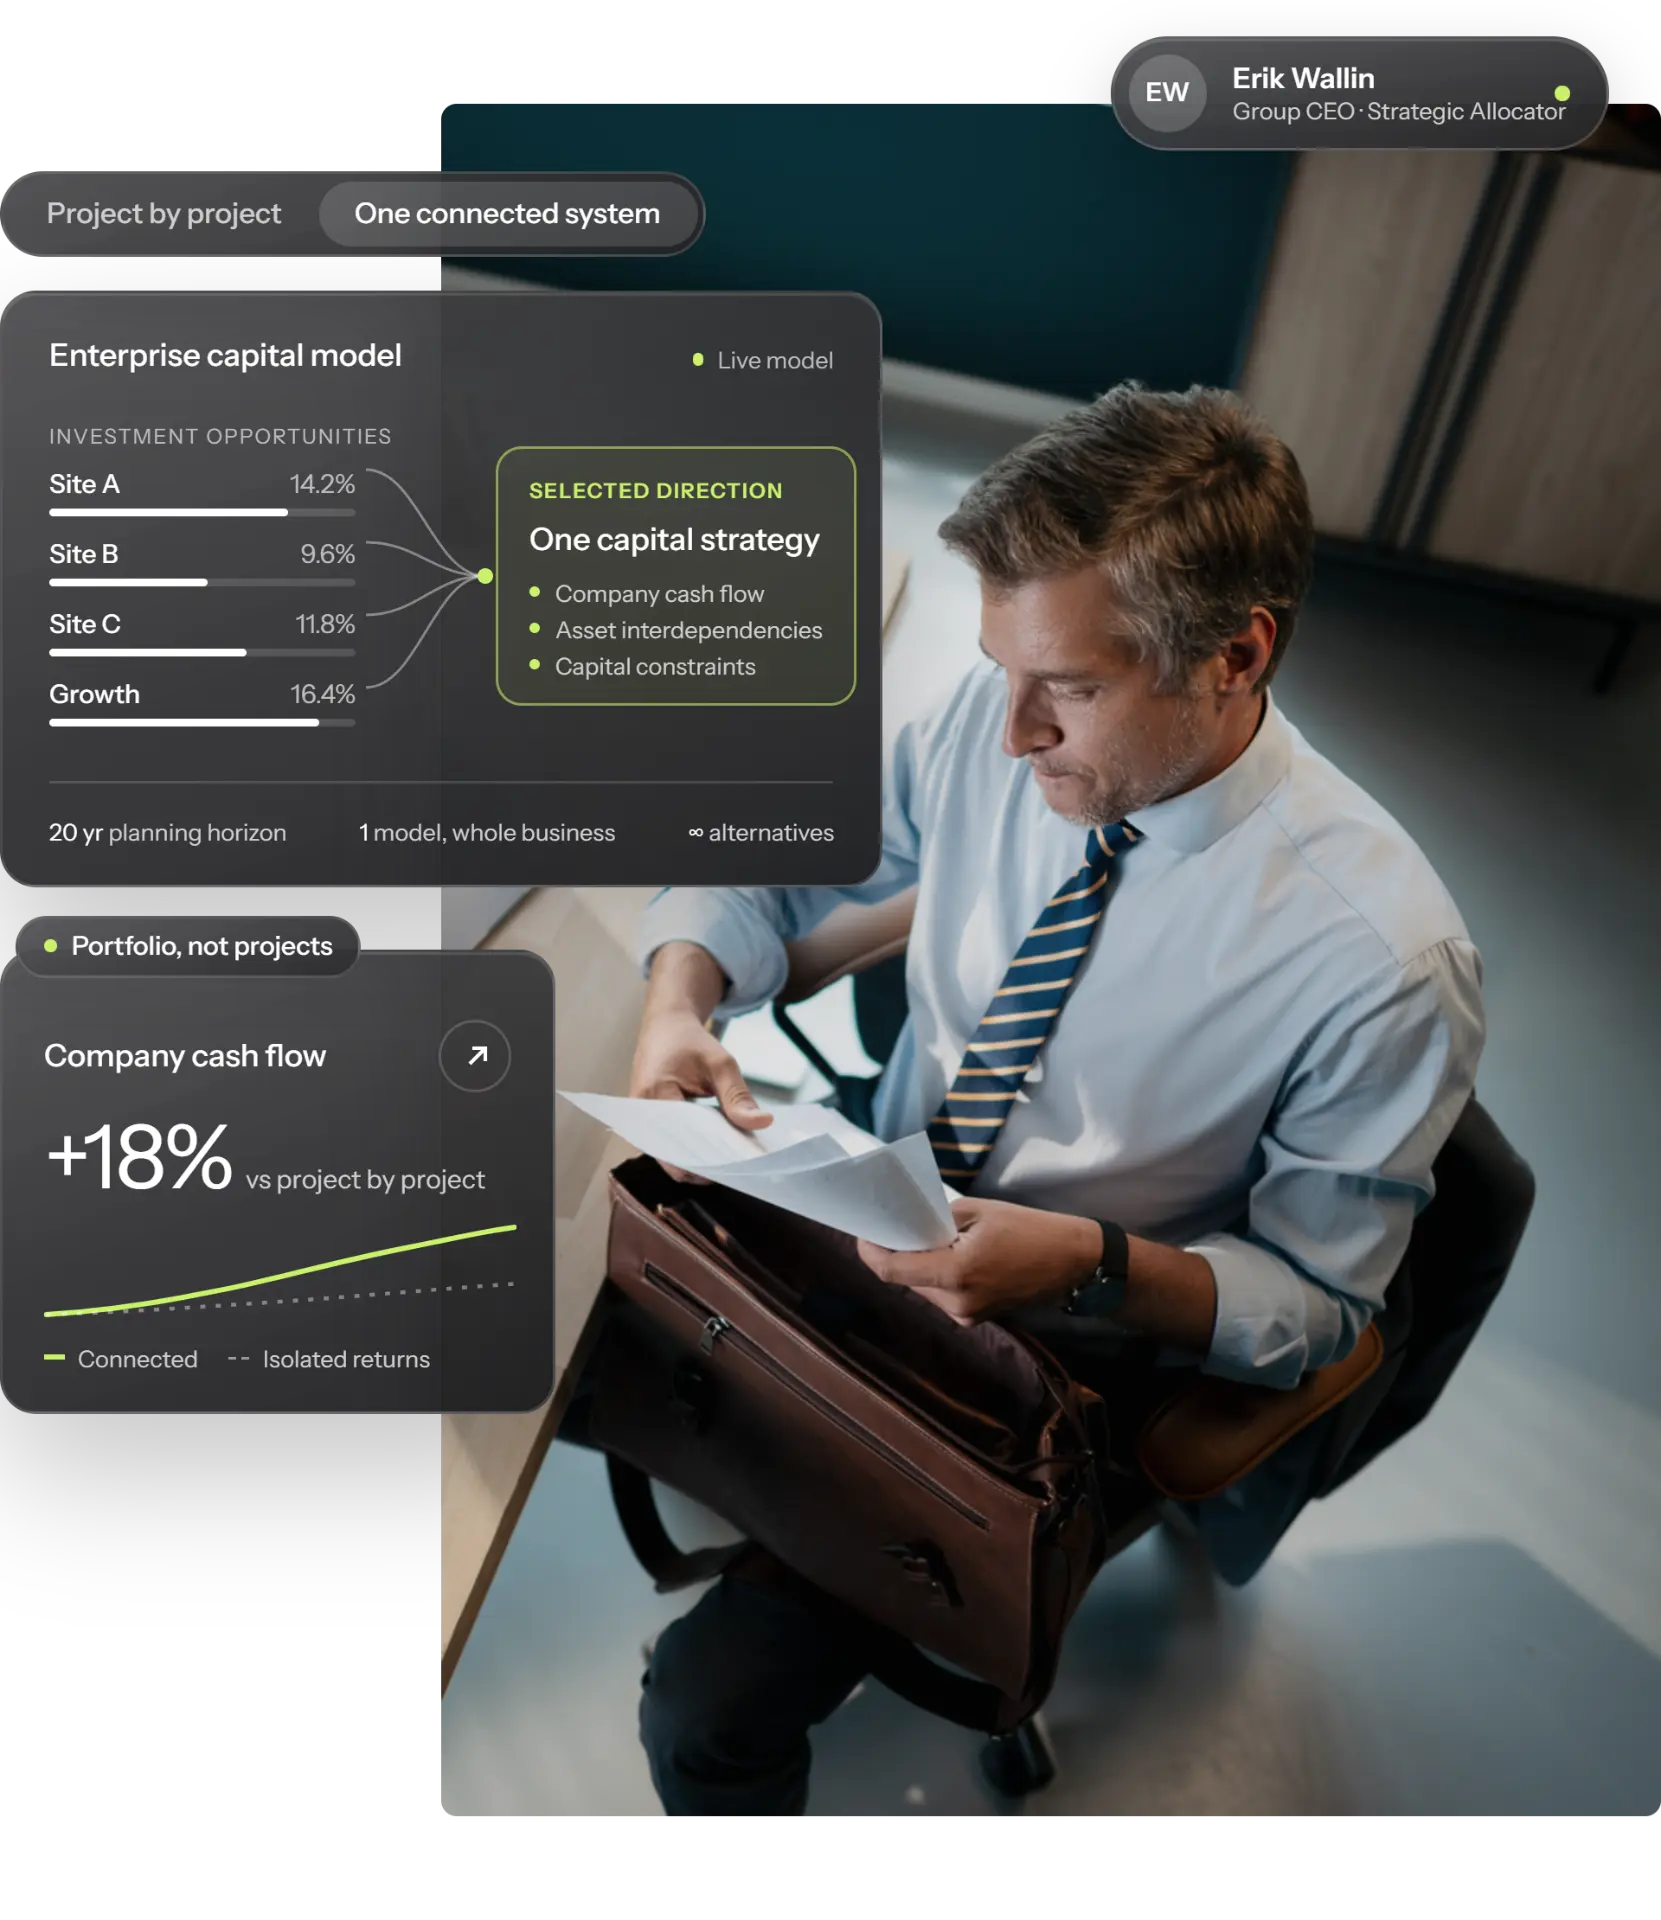
The question is not only whether each project is attractive. It is whether the combined portfolio maximises long-term company cash flow.
Definition
Strategic capital allocation is the process of directing capital toward the combination of investments and asset decisions that delivers the strongest long-term cash flow for the company as a whole.
Unlike project-by-project appraisal, a systems approach evaluates the portfolio as a whole. It models dependencies, compares complete alternatives and makes trade-offs visible before the budget is committed.
Why it happens
NPV, IRR and payback can all be useful measures. The error is treating the strongest individual project cases as if they automatically create the strongest company outcome.
The further an asset is from state of the art, the worse that comparison looks, and the higher the investment scores. The weakest sites produce the strongest cases, and they submit the most requests. The approach systematically favours older assets over newer, potentially more valuable ones.
Sites identify real needs, but no site is responsible for weighing its request against opportunities elsewhere in the business.
Each project is compared with not doing that project, rather than with everything else the same capital could achieve.
Dependencies and trade-offs remain hidden when decisions are assessed one at a time instead of as a connected portfolio.
Project returns and asset-level ratios do not answer the strategic question of whether capital belongs at that asset at all.
The strategic disconnect
Executive teams may agree which assets have a future and where the company should grow. Then the budget cycle begins with a list of individually positive business cases, and the two conversations never meet.
Approving each business case on its own merits still skips the comparison that matters.
Company strategy
Strategic alternatives
Chosen capital direction
Budget and approvals
Execution and feedback
The method
Weissr models needs, opportunities, greenfields and acquisitions for what they do to the business together. Complete strategies are measured against the company as it operates today and compared over the relevant planning horizon, which in some industries is 20 years or more.
| Decision dimension | Traditional project evaluation | Systems approach |
|---|---|---|
| Unit of analysis | Each investment judged on its own merits | All investments evaluated for their combined effect |
| Dependencies | Interdependencies are not represented | Interdependencies between investments are modelled |
| Alternatives | The main alternative is not doing the project | Multiple whole-business alternatives share one baseline |
| Primary measure | Project payback, NPV or IRR | Company cash flow over the planning horizon |
| Role of strategy | Strategy emerges from approved requests | Strategy is decided first and governs requests |
From method to decision
Weissr Capex Strategy holds the model of the asset base and builds strategic alternatives on top of it. Leadership can compare whole-business directions, test scenarios and sensitivities, and decide which portfolio best supports the company’s future.
Alternative comparison
Company cash flow over the planning horizon
Built on real capex experience
What it delivers
A systems approach can boost long-term company cash flow by 20–100%, by directing capital toward the combination of assets and opportunities that creates the strongest whole-company outcome.
Show the alternatives considered, the assumptions behind them and the financial consequence of the chosen direction.
Give sites and functions one explainable direction instead of asking them to compete through isolated business cases.
Decide the strategic direction first, then let that direction govern what enters capital planning and approval.
See the value forgone when capital, cash flow or another constraint forces the portfolio away from the strongest alternative.
Re-optimise against the same living model as prices, demand, costs and assumptions move.
Guides and reports
Report
How capital-intensive companies free up cash by tightening the link between strategy, budgets and project execution.
Download the report →
Article
Why individually sound capex projects can create a weak portfolio, and how a systems approach reconnects the capex process with capital allocation strategy.
Read the article →
Book
Fredrik Weissenrieder and Daniel Lindén's book, published by McGraw Hill in 2022, sets out the methodology behind this page.
About the book →Set direction
Model the asset base and compare whole-business alternatives on company-wide cash flow.
Build the portfolio
Translate the chosen strategy into a governed capital portfolio.
Executive perspective
Connect company strategy, capital allocation and business performance.
Execute the decision
Govern approvals, spend and delivery once capital is committed.
By role
Turn allocation choices into a defensible capital plan.
By role
Run the planning cycle that delivers the allocation.
Capex Maturity Assessment
Answer a short set of questions on process, data, visibility and cash flow, and get a report showing your level in each area.
Take the assessmentCapital allocation FAQ
A systems approach evaluates investments together for their combined effect on company cash flow. Instead of ranking isolated projects, it compares complete strategic alternatives for the whole business and sets the direction that creates the strongest long-term outcome.
Not necessarily. Payback measures how quickly one project returns its own cost; it does not measure what that decision does to the company as a whole. A portfolio can contain projects with longer paybacks while producing stronger company cash flow over the planning horizon.
The problem is often not discipline. Individual requests can be accurate, well governed and delivered as promised while the combined portfolio still directs capital away from the best long-term company outcome. Strong governance confirms that each decision followed the process. It says nothing about whether the set of decisions was the best use of the capital.
The amount of capital does not have to change. Part of the improvement comes from reallocating it toward the combination of assets and opportunities that generates more cash flow over the life of the strategy. Just as much comes from avoiding investments that look necessary but stop being necessary once the system is set up differently.
The method does not depend on one forecast being right. Strategic alternatives are compared on common assumptions and measured on the cash flow of the company as a whole. Prices, demand, costs and capex needs are then varied in sensitivity analyses to see which alternative holds up best across conditions, rather than which one looks best under a single set of numbers.
It requires a model where the assets, capacities and costs hang together, so the effect of one change on the rest is visible. Decisions are then made by comparing complete alternatives on company-wide cash flow rather than by assessing proposals one at a time. In practice this also means accepting that a project with a weak return of its own can still be the right one for the company.
See how Weissr compares complete strategic alternatives and turns company direction into investment decisions.
Book a demo